The short verdict
For most medical and dental practices, the best loan depends on the purchase. Clinical equipment and surgery fit-outs usually suit equipment finance, because the gear secures the loan. Buying into or acquiring a practice suits a term loan sized on the practice's earnings, often with property support. Owning your rooms suits a commercial property loan, and a line of credit covers gaps between billing and payment.
At a glance
- Equipment finance is usually the best fit for chairs, imaging and sterilisation gear.
- Practice purchases are mostly goodwill, so lenders look hard at earnings.
- Fit-outs with plumbing and shielding are costly and hard to move.
- A line of credit smooths the gap between treating patients and being paid.
- Typical needs
- Clinical equipment, fit-out, practice purchase, rooms
- Assessed on
- Practice financials, billings, registration, time in practice
- Security
- The equipment, a guarantee, or property for larger amounts
- Speed in words
- Equipment can move quickly; acquisitions take weeks
Loans for medical and dental practices are business finance used by GPs, specialists, dentists, physios, vets and allied health owners to buy clinical equipment, fit out rooms, buy into or acquire a practice, or purchase premises. The best loans for medical and dental practices are the ones whose security and term match what you’re buying, because a dental chair, a share of goodwill and a building are three very different assets.
Why are health practices a distinct kind of borrower?
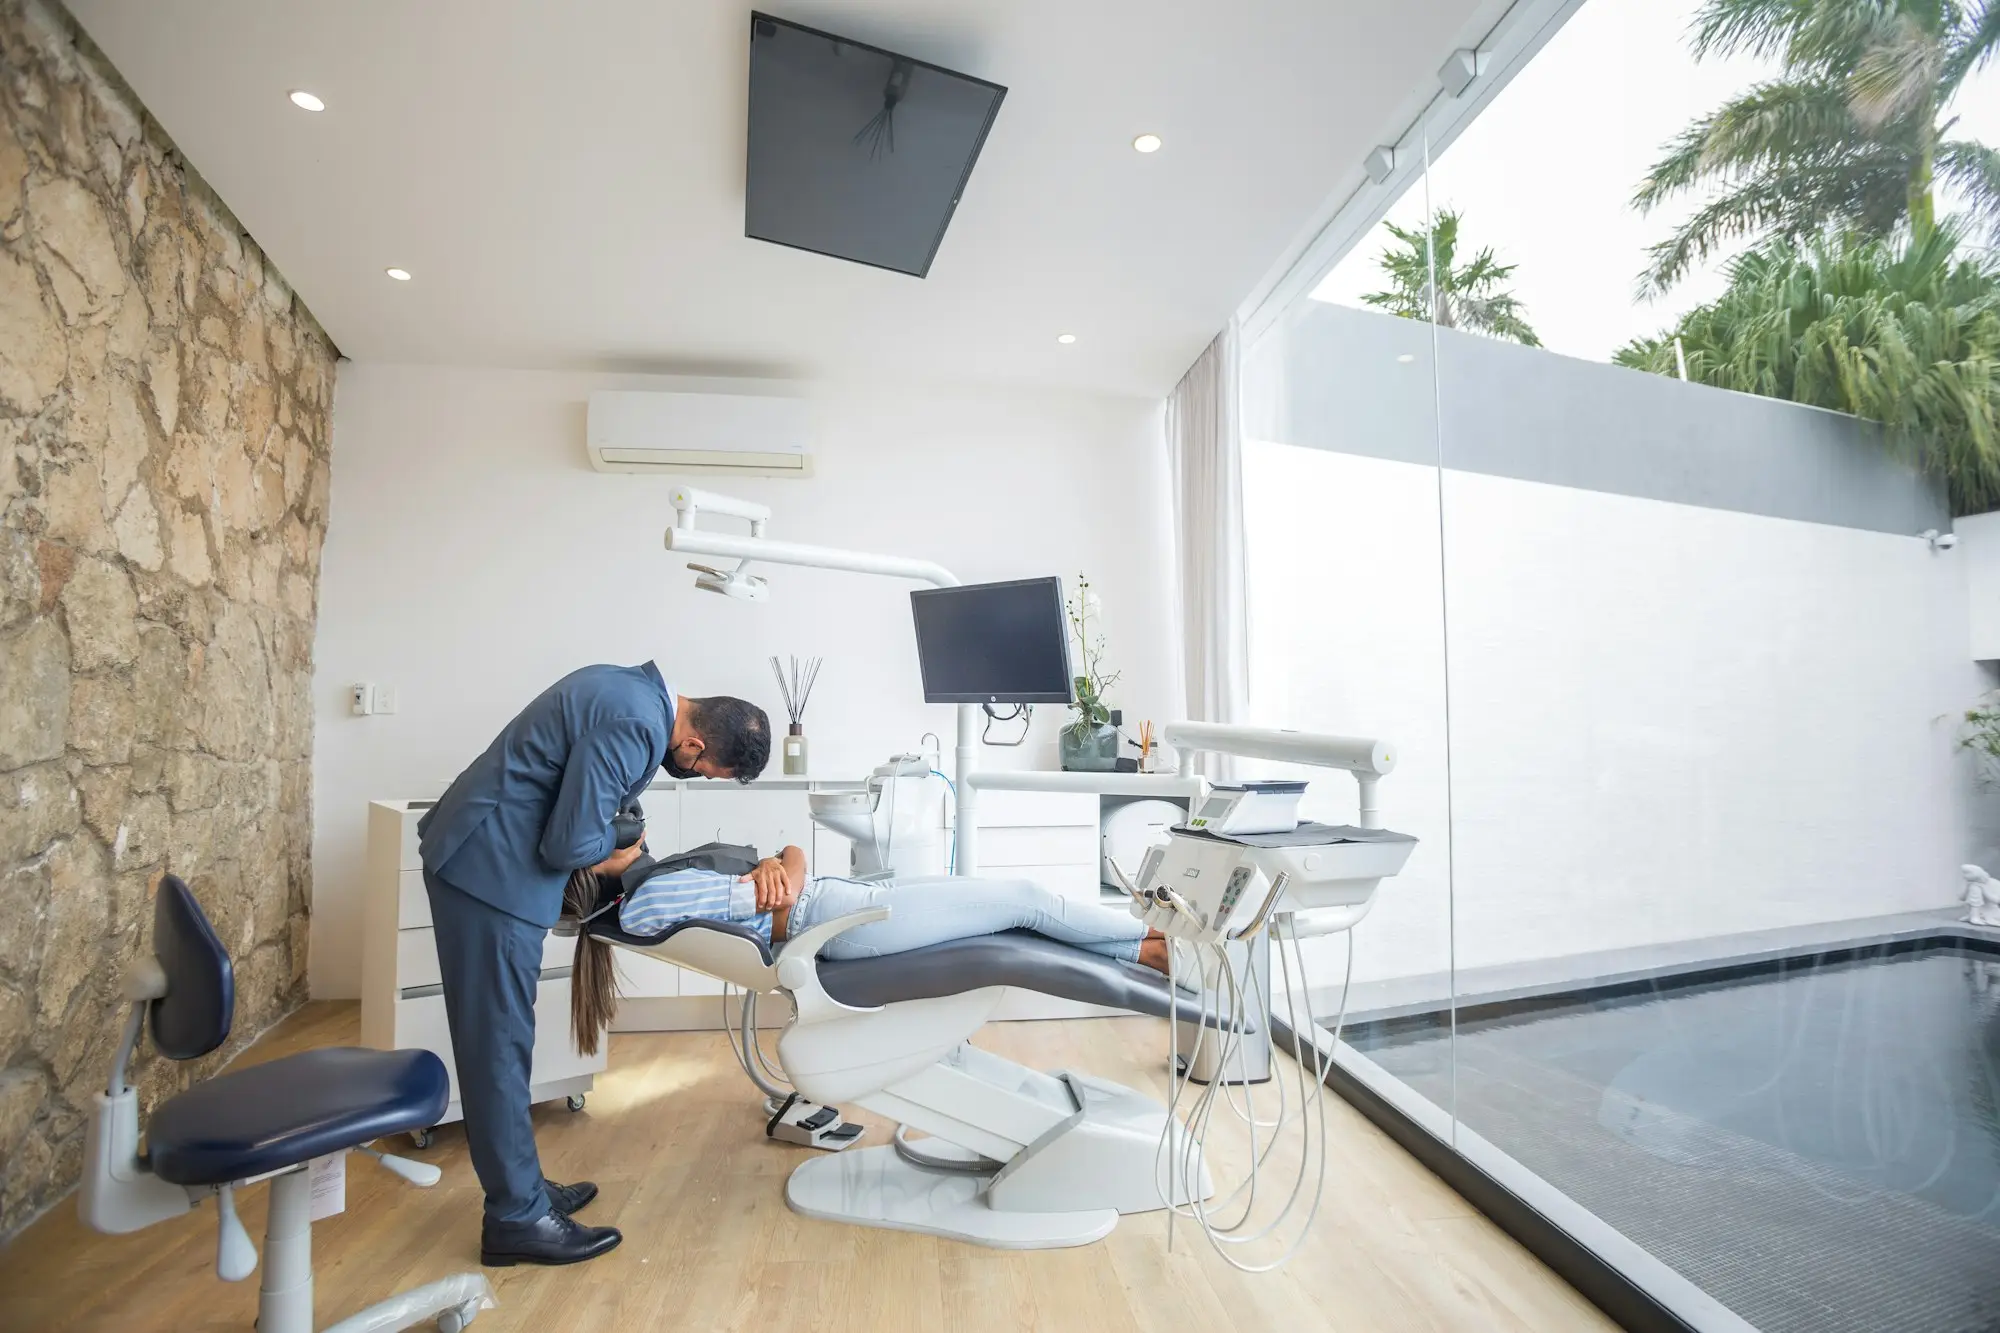
Because their earnings are steady but their purchases are lumpy and expensive. Patient demand tends to hold up through economic cycles, which lenders like. The pressure comes from the capital side: a single imaging unit, a dental chair package or a sterilisation room can cost more than a small business spends on equipment in a decade.
Health is also a growing part of the economy. The ABS Counts of Australian Businesses for June 2026 shows health care and social assistance businesses rose 6.7% over the year to 227,702, one of the strongest increases of any industry. More practices means more owners buying in, buying out and fitting out.
Typical borrowing needs include:
- Clinical equipment. Chairs, X-ray and imaging, lasers, autoclaves, practice software.
- Fit-outs. Plumbing for every surgery, lead shielding for imaging, compliant sterilisation areas.
- Practice purchases. Buying a retiring principal’s share, or acquiring a whole practice.
- Premises. Buying the rooms you’ve rented for years.
- Working capital. Covering wages and costs while claims and patient invoices are paid.
What do lenders look at for a medical or dental practice?
They look at the practitioner and the practice together. Expect questions about your registration and years in practice, the practice’s financial statements and billings, the number of practitioners and patient base, the lease on the rooms and any existing finance. For an acquisition, the sale or partnership agreement and the vendor’s figures carry a lot of weight.
A principal with a solid billing history, financials up to date and a clear plan for the purchase is a file most lenders understand well.
Which loans are best for medical and dental practices?
We graded four structures using the tests in how we judge, for an established practice.
| Practice need | Structure | Security | Fit | Total cost | Paperwork | Flexibility |
|---|---|---|---|---|---|---|
| Chairs, imaging, sterilisation | Equipment finance | Strong | Strong | Strong | Strong | Fair |
| Buying into or acquiring a practice | Goodwill term loan, often property-supported | Fair | Strong | Fair | Weak | Fair |
| Owning the rooms | Commercial property loan | Fair | Strong | Strong | Weak | Fair |
| Gaps between billing and payment | Line of credit | Fair | Strong | Fair | Strong | Strong |
1. Our pick for equipment and fit-outs: equipment finance
Clinical equipment is exactly what asset finance was designed for. The item secures the loan, the term can match its working life, and your home stays out of it. Many fit-out components can also be financed this way when they’re tied to equipment. Eligible assets under $20,000 may be fully deductible under the ATO’s instant asset write-off, now permanent for businesses with aggregated turnover under $10 million. Our chattel mortgage or lease verdict helps you choose between ownership and upgrade-friendly leasing.
2. Our pick for acquisitions: a term loan sized on earnings
Buying into a practice is mostly buying goodwill, a stream of future earnings that a lender can’t easily sell. That’s why lenders size these loans on the practice’s profit and often ask for property support on larger amounts. Expect a thorough process. Our verdict on buying a business covers how to prepare.
3. For owning your rooms: a commercial property loan
If you plan to stay put for many years, buying your rooms swaps rent for equity. It needs a deposit, stamp duty and legal costs, and it ties up capital you might otherwise spend on equipment. Read our commercial property loans verdict before you commit.
4. For working capital: a line of credit
A line of credit suits the timing gaps in a practice, such as a slow month of claims, a new associate’s first weeks or a large supplier order. Draw and repay as needed.
Our verdict
Medical and dental practices: the verdict
- Best for
- Equipment and fit-outs on equipment finance; practice acquisitions on an earnings-based term loan; rooms on a commercial property loan; timing gaps on a line of credit.
- Not for
- Funding a goodwill purchase on short-term unsecured loans, or tying up the practice's working capital in a building purchase it can't yet afford.
- Check before you sign
- The payback figure in dollars, balloons and residuals on equipment, what happens to the loan if a partner leaves, and the costs of upgrading equipment mid-term.
If you’re weighing a new chair, an acquisition or your own rooms, ask a specialist which structure suits. The first conversation involves no credit check.
Illustrative example: a dentist buys into her practice
Illustrative only. An associate dentist has worked at a two-chair practice for six years. The principal offers her a half share for $600,000, and the practice also needs a third surgery fitted out for about $250,000.
- Half share: a term loan sized on her share of the practice’s profit, supported by equity in her home for part of the amount.
- Third surgery: equipment finance over seven years, secured by the chair, imaging and cabinetry, with repayments shared through the partnership.
- Working capital: a modest line of credit in the practice’s name to cover the new associate’s first months.
Verdict for this owner: three structures, each tied to a different kind of asset. Putting all of it on one loan secured by her home would have mixed long-term goodwill with gear that will need replacing in a decade.
Should a practice pay cash for equipment or finance it?
Paying cash avoids interest, but in a practice it often costs more than it saves. Cash spent on a chair or scanner is cash that can’t cover a new associate’s first months, a slow quarter or the deposit on your rooms. Financing spreads the cost across the years the equipment earns, keeps reserves intact and leaves the decision about upgrading open. The exception is a modest item the practice can buy without denting its buffer, where paying outright is usually the cheaper path. The test is simple: after the purchase, could the practice still cover two months of wages and rent from the bank account? If not, finance it.
How much can a medical or dental practice borrow?
Equipment finance is sized mainly on the item and the practice’s ability to repay. Unsecured and line-of-credit options for trading businesses typically range from $5,000 to $500,000, depending on turnover and bank statements. Larger acquisitions and premises usually rely on property, and property-secured business loans run from $20,000 to $5,000,000 against residential or commercial security.
What should a practice owner prepare before borrowing?
- Two years of practice financials and recent BAS lodgements.
- Quotes and specifications for equipment or fit-out works.
- The sale or partnership agreement and vendor figures for any acquisition.
- Your lease, including term and options, because lenders won’t lend past it comfortably.
- A list of current finance, including equipment loans already running.
It also helps to think about what happens if the plan changes. If a partner leaves, who carries the loan? If you upgrade equipment early, what’s the payout? Settling those questions before you sign avoids expensive surprises. Our business equipment verdict has more on upgrade terms.
Ready to see what your practice could arrange?
Whether it’s a chair, a buy-in or the building, start a 60-second enquiry about your practice and we’ll work through the right structure for each part.
You won’t face a credit check at the first step, your enquiry isn’t distributed to a roster of lenders, and a real person handles it from start to finish. Accurate figures on billings, existing loans and the purchase price let us match you properly from the outset. Compare other verdicts on the best business loans hub.
Questions owners ask
What is the best way to finance dental equipment?
For most practices, equipment finance such as a chattel mortgage or lease, because the chair, imaging unit or steriliser secures the loan and the term can match its working life. Compare offers on the total repayable, any balloon at the end and the cost of paying out early if you upgrade.
How do I finance buying into a medical practice?
Usually with a term loan sized on the share of earnings you're buying, often supported by property security for larger amounts. Lenders want the practice's financials, the partnership or sale agreement and evidence that patient numbers will hold. Your own contribution strengthens the application.
Can a newly qualified practitioner get a practice loan?
It's possible, particularly for equipment and fit-out, but lenders will look at your registration, experience and the practice's history rather than your own trading record. Buying into an established practice is usually easier to fund than starting a new one from scratch.
Should a practice buy or lease its rooms?
Buying builds equity and stops rent rises, but ties up capital and adds stamp duty, legal costs and maintenance. Leasing keeps money free for equipment and staff. Buying suits established practices planning to stay in one location for many years.
Can a practice borrow to cover a gap in cash flow?
Yes. A line of credit is generally the best fit, because it can be drawn when claims or invoices are slow and repaid when they arrive. Avoid fixed-term loans for recurring gaps, as you'll pay for money you only need for a few weeks.
Reviewed by the Best Biz Loan editorial team · updated 5 October 2026
We judge loan structures and lender types against the same five tests, never named lenders' products, and we never publish rates. How we judge